
Will My Insurance Cover a New Roof?
Understanding what your policy actually covers before damage happens saves significant time and money when a claim is needed.
Will My Insurance Cover a New Roof? A 2026 Homeowner's Guide
Homeowners insurance typically covers a new roof when the damage is caused by a sudden, covered event such as hail, wind, fallen trees, fire, or vandalism, and not by gradual wear, age, or lack of maintenance. The exact coverage depends on the policy, the cause of damage, the roof's age, and the carrier's rules in the state where the home is located. Many policies that covered roof replacement easily a decade ago now have specific limits, age-based exclusions, and material-based deductibles that homeowners only discover when they file a claim.
This guide covers what's typically covered, what isn't, how roof age affects coverage, what carriers look for during inspections, and how impact-resistant credentials change the long-term cost picture.
Standard Homeowners’ insurance generally covers damage from sudden, covered events:
Hail damage that creates impact bruises, granule loss, or shingle cracking.
Wind damage that lifts, tears, or removes shingles.
Fallen trees or large branches that damage the roof structure.
Fire damage to the roof.
Vandalism or accidental damage from third parties.
Water damage that follows directly from a covered event (e.g., rain entering after a hailstorm displaces shingles)
"Covered" doesn't always mean "fully paid." Most policies pay the cost of repair or replacement minus the deductible, and some have separate, higher deductibles for wind and hail specifically sometimes calculated as a percentage of the home's insured value rather than a flat dollar amount.
What Homeowners’ insurance typically does NOT cover
Gradual wear and aging — shingles that have reached the end of their natural life.
Lack of maintenance — damage that could have been prevented by reasonable upkeep.
Manufacturer defects — covered by the shingle manufacturer's warranty, not the homeowner's insurance.
Cosmetic damage that doesn't affect the roof's function increasingly excluded in newer policies, especially in hail-prone states.
Pre-existing damage — damage that existed before the policy started or the recent event.
Damage from poor installation by the original roofing contractor.
This is where many homeowners get blindsided. A 20-year-old roof that finally fails isn't a claim event; it's simply reaching the end of its service life. The solution is preventative maintenance, not an insurance claim.
How roof age affects insurance coverage
Roof age has become one of the most consequential factors in Homeowners’ insurance in 2026. Three things to understand:
1) Many carriers now exclude or limit older roofs
In states with high hail or hurricane exposure such as Florida, Texas, Oklahoma, Colorado, and a growing list of others; many carriers won't write new policies for roofs older than 15 or 20 years.
Some non-renew existing policies when the roof crosses that threshold. The exact rule varies by carrier and state, but the trend is consistent: older roofs are increasingly viewed as a claims risk and priced or excluded accordingly.
Across the GoNano Contractor network, homeowners reporting policy non-renewals due to roof age have increased noticeably over the past two years. What began in Florida is now becoming a nationwide trend.
2) Actual Cash Value vs. Replacement Cost coverage
Policies on older roofs are increasingly written as Actual Cash Value (ACV) rather than Replacement Cost Value (RCV).
Actual Cash Value (ACV)
Pays the depreciated value of the roof at the time of loss, which on a 20-year-old roof might be only 20% of the replacement cost.
Replacement Cost (RCV)
Pays the full cost to replace with a new roof of equivalent quality.
A homeowner expecting an RCV payout and discovering they have ACV coverage faces a major surprise at claim time.
3) Inspection requirements at renewal
Carriers increasingly require roof inspections at policy renewal sometimes annually for older roofs. Roofs that fail the inspection may be subject to non-renewal, coverage modification, or required remediation. A roof that's been kept up well, with documented maintenance, passes these inspections far more often than a neglected one.
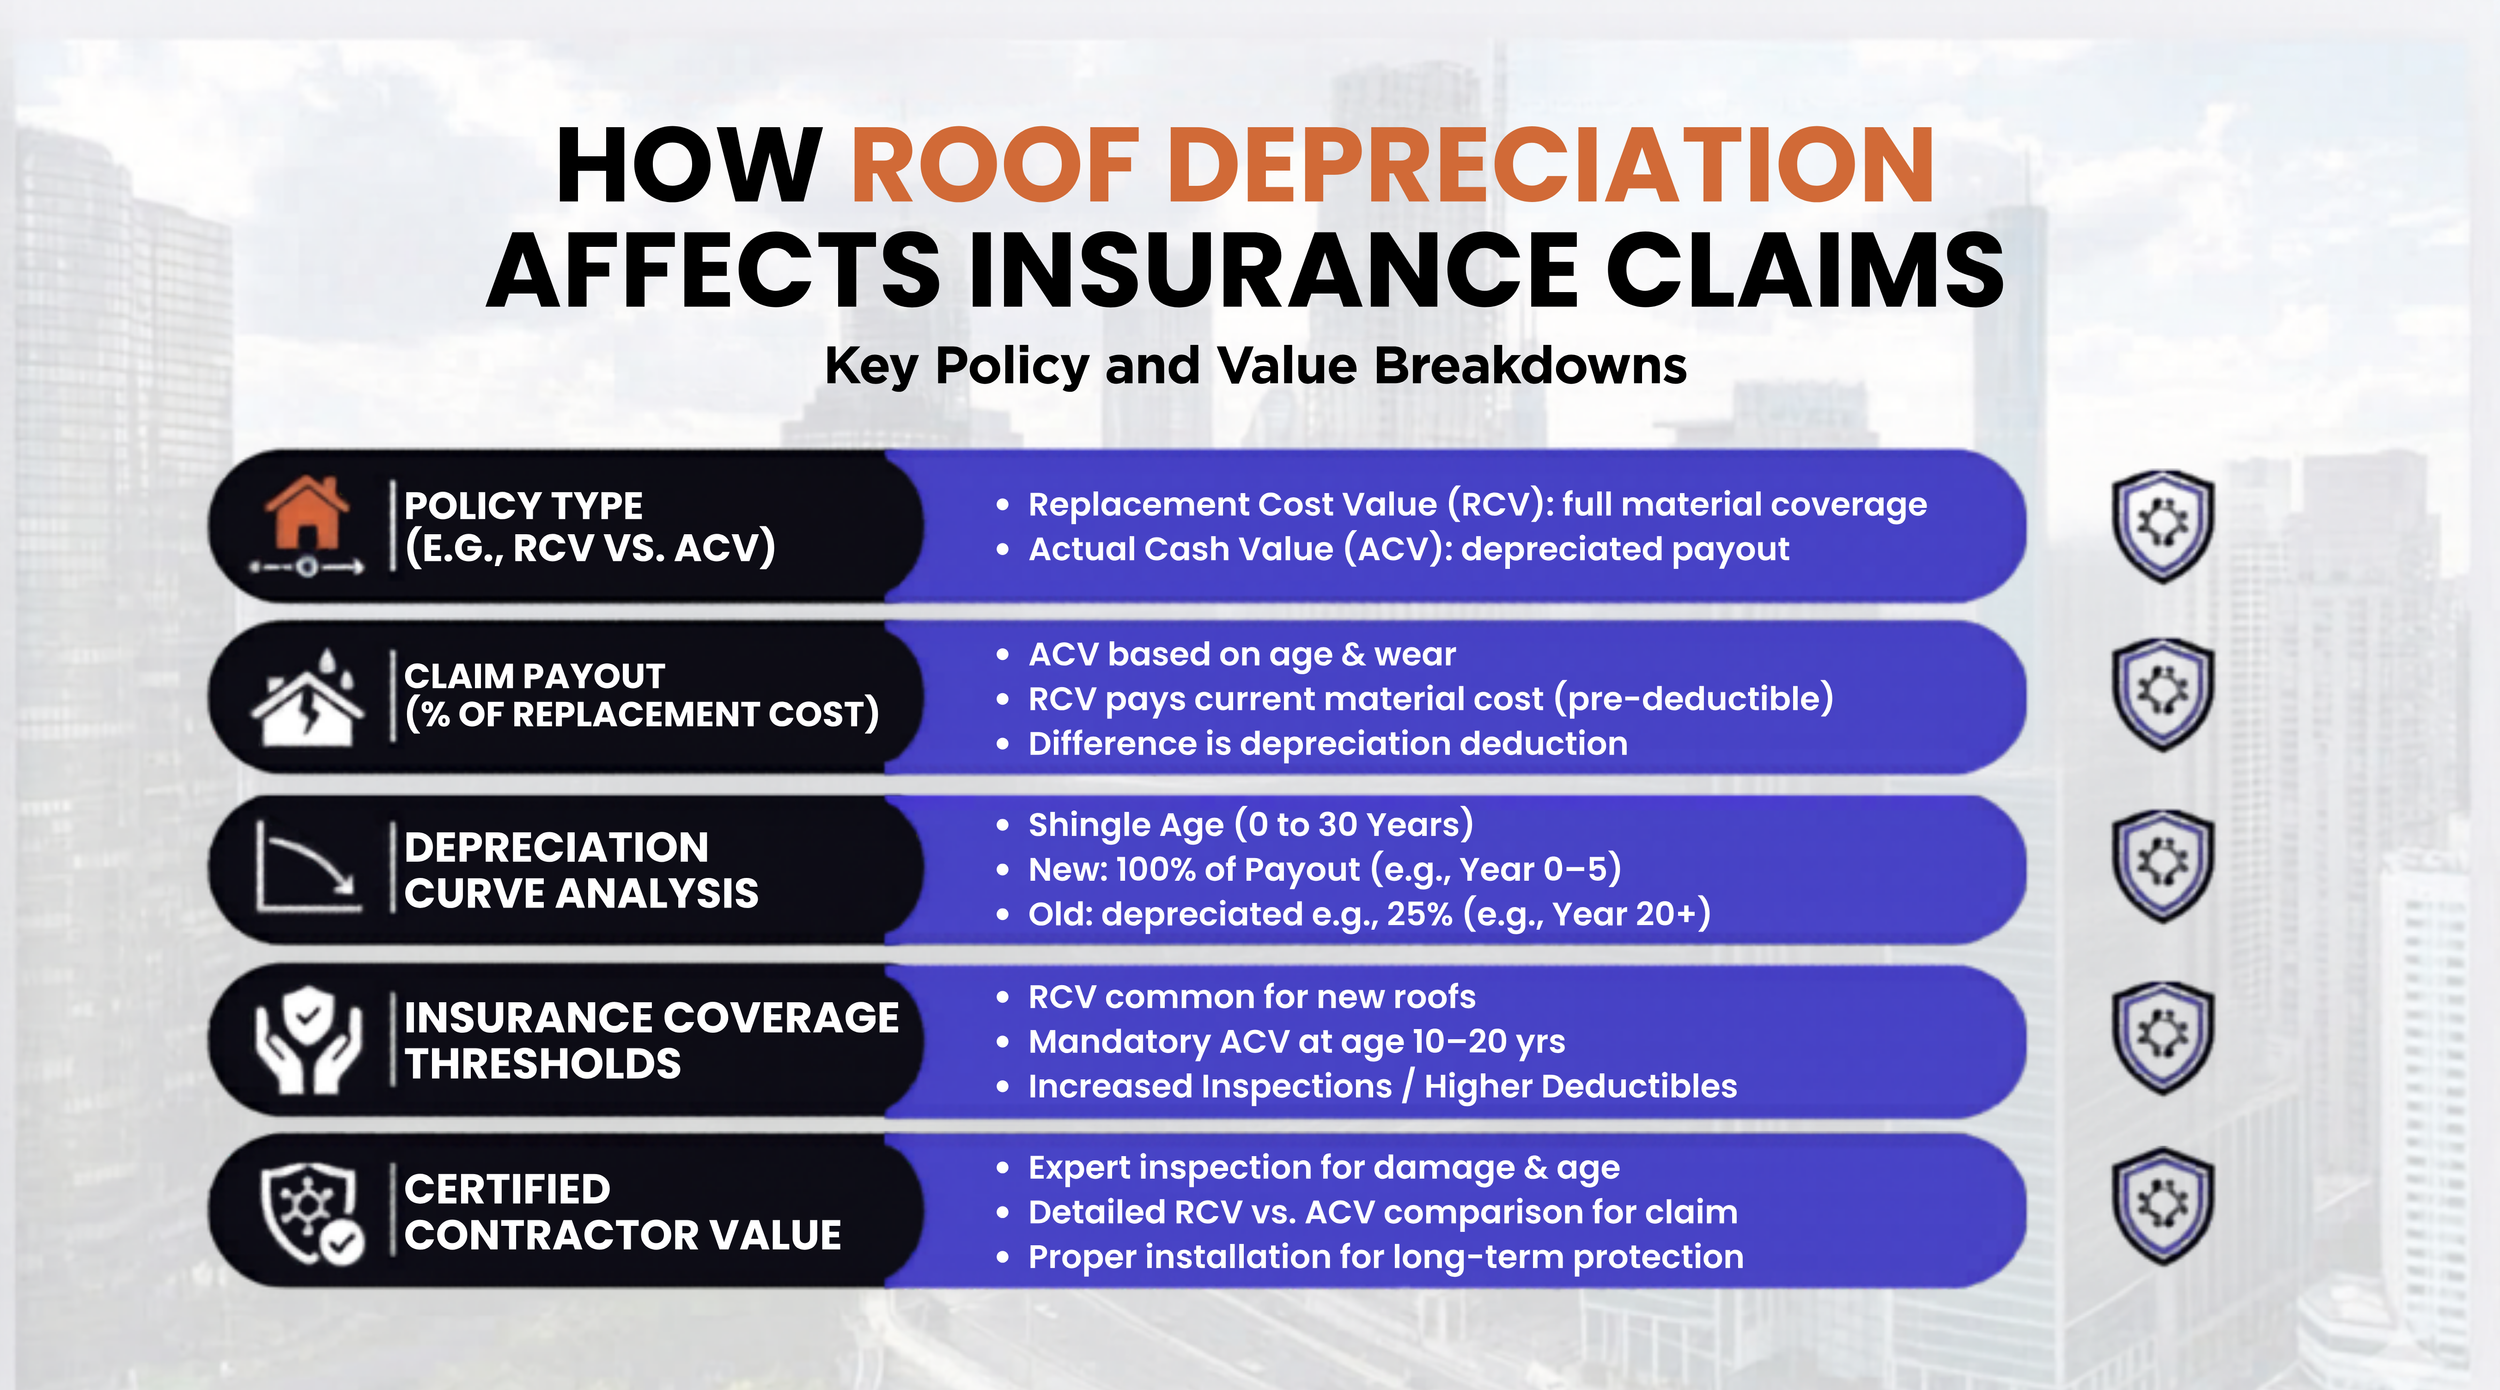
Roof age has become one of the most consequential factors in Homeowners’ Insurance older roofs face exclusion, non-renewal, or reduced coverage.
How roof age affects insurance coverage
When a carrier inspects a roof at claim time, at renewal, or before issuing a new policy, they're looking at five things:
Overall condition and apparent remaining life.
Evidence of past damage and whether it was properly repaired.
Granule coverage and shingle integrity.
Flashing, sealant condition, and penetration integrity.
Documentation of maintenance and any improvements (ventilation upgrades, impact- resistant materials, etc.)
A roof that's been treated with a documented improvement like Gonano’s Structural Roof Rejuvenation with independent third-party testing and a hard transferable warranty provides exactly the kind of documentation carriers value: a recent, credentialed investment in the roof's structural integrity.
In one recent case, a homeowner facing non-renewal in Texas was retained on the
policy after providing documentation of the NuRoof Revive installation and the
10-year hard transferable warranty.